Financial statement spreading
Compare the statements without losing the detail that explains them.
SpreadSpace™ organizes supported financial statements into a review of earnings, liquidity and repayment capacity. Compare reporting periods, inspect source-backed figures and bring supporting schedules into the discussion.
Work with balance sheets, profit and loss statements and cash flow statements, alongside supported aging reports, debt schedules and personal financial statements.
Build a view that keeps its context
A comparison is only useful when the reviewer understands what is being compared. Keep the company, reporting period and source document attached to the financial information.
SpreadSpace brings the statements into an organized analysis so the reviewer can examine performance across the supplied periods and then return to the supporting evidence. A chart can show the change; the source helps explain it.
Public filings and private statements
Audited, reviewed and management-prepared statements enter the same review as a 10-K or 10-Q. A public filing is read as it was published, from the HTML, the PDF or the Excel financial report, with the primary statements and the notes behind them.
The notes tables are read as tables of their own. Debt maturities, lease obligations, the income tax provision and the rollforwards of equity, allowances and intangibles each keep their figures, so a total on the balance sheet can be followed into the note that itemizes it.
Public and private statements keep their own company, period and source. A comparison across them is the analyst's call, made with both documents in view.
Read the components behind the total
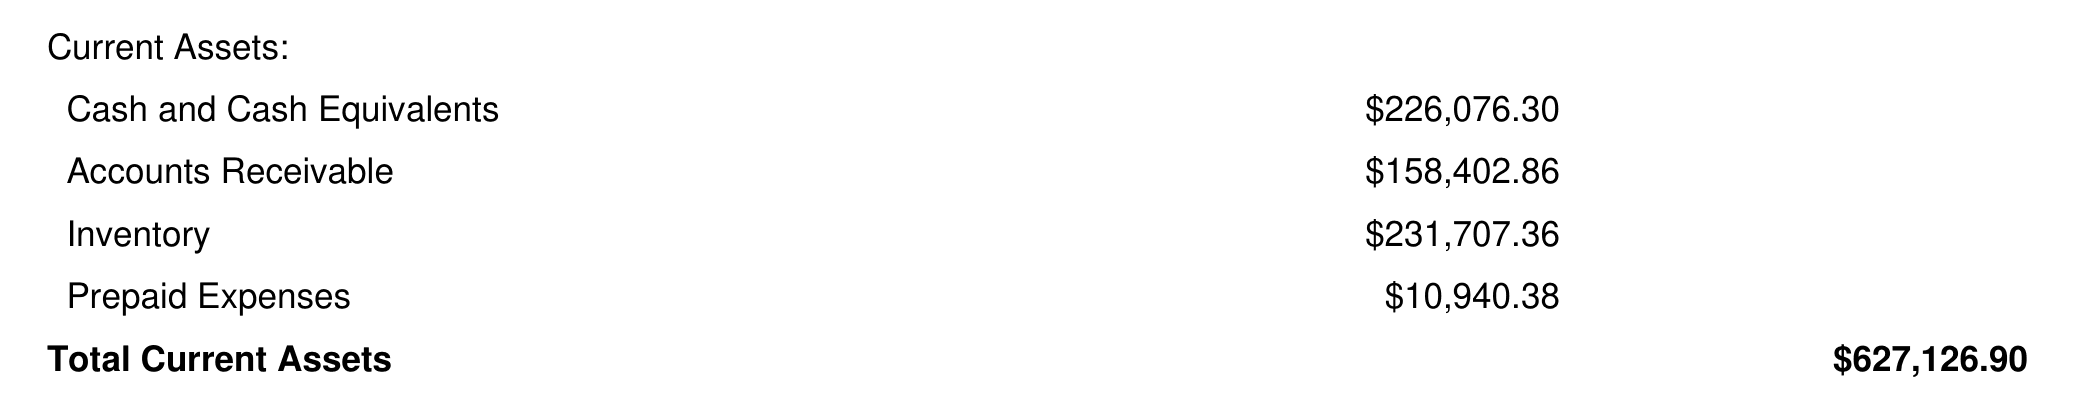
A current-assets figure may combine cash, receivables, inventory and other amounts. Those components are not interchangeable simply because they appear under the same heading.
Use source review and available component detail to examine what supports a total. The same approach applies when a liability amount needs to be understood before it is used in an assessment of repayment capacity.
For supported derived figures, inspect the contributing rows rather than treating the summarized amount as self-explanatory.
Trusted by auditors
See Joseph's testimonyEvery number in the spread traces back to the source. So does every component behind it.
When a loan goes into default a year or two after origination, the numbers in the file have lost their context, and an examination can run anywhere from several hours to several days depending on how much paperwork the deal involved.
SpreadSpace preserves that context in the spreads and the memos: every number traces back not just to its highlighted line on the source document, but to the components that make up that number.
I'm not hunting for the pieces of an operating lease liability — the entire composition is in front of me in three seconds, right on the return or the financial statements. It's absolutely brilliant.
Connect working capital to the schedules
Bring accounts receivable and accounts payable aging reports alongside the financial statements. Review the supplied balances and aging detail when investigating the company's working-capital position.
For example, a higher receivables balance invites a different conversation when the supporting report shows that more of the balance is overdue. The point of connecting the schedule is to let the analyst examine that question, not to substitute an automatic conclusion for the review.
Keep the reporting dates in view when comparing a schedule with the statement it is being used to explain.
Examine changes across the periods provided
Compare revenue, expenses, earnings and balance-sheet movements. Use available monthly detail to investigate changes that a year-end comparison may leave unexplained.
An increase or decrease is a starting point for questions. Is the comparison over equivalent periods? What contributes to the movement? Does another document provide context? The workspace keeps the financial view and source review connected while the analyst works through those questions.
Bring earnings and obligations into coverage analysis
Review the selected earnings basis, analyst adjustments and debt service together. Compare a historical view with a pro forma view that includes proposed debt, keeping the assumptions available for the discussion.
A coverage figure should be explainable through the inputs used to calculate it. The analyst determines which supported inputs and adjustments belong in the loan's analysis.
Check the mathematics without hiding exceptions
For supported documents, SpreadSpace checks extracted figures against the mathematical relationships available in the document. An extraction that does not meet validation requirements is rejected. A retained extraction with a discrepancy includes an explicit notice for review.
Passing an arithmetic check does not establish the quality of the borrower's financial reporting or resolve every question in the credit file. Use it alongside the source and the analyst's review.
Turn the analysis into a reviewable explanation
Bring selected financial exhibits into the credit memo and write the explanation around the analysis. In the workspace, source-linked figures remain available when a reviewer wants to inspect the supporting detail.
The benefit is not simply another summary. It is a path from the summary to the information needed to understand it.
Financial statement document details
Explore the statements, aging reports, debt schedules and personal financial statements available for review. Integration details are in the docs.spreadspace.app.
Balance Sheet
Statement Spine
Every line item
Current Assets
Non-current Assets
Current Liabilities
Long-term Liabilities
Equity
Total Liabilities and Equity
Every period side by side
Standardized line names
Drill down from any total to its lines
Arithmetic checks on every subtotal
Audited, reviewed or compiled
See what supports the spread
Bring a statement package and its supporting schedules. Review a material change, inspect the components behind a total and follow the evidence into the credit memo.